Find Better Auto Car Loans Near Me Without the Runaround
Auto car loans near me are easiest to find when you compare local credit unions, banks, and dealership financing before you choose a vehicle. Start with your budget and credit, request prequalification or preapproval online, then compare the full loan offer – not just the monthly payment.
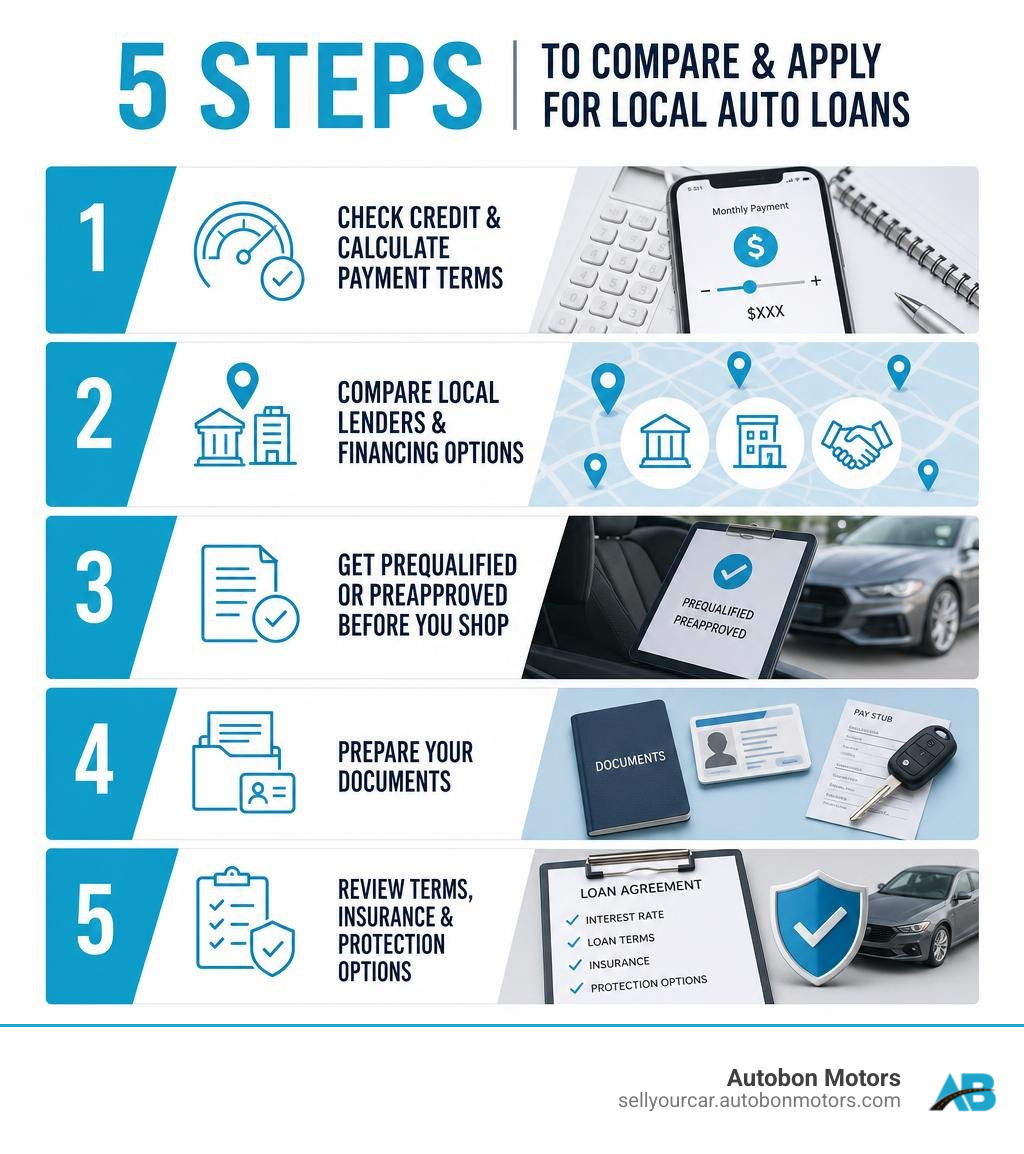
Here are the five critical steps this guide covers:
- Check your credit and estimate a payment you can afford.
- Compare local lenders and financing options.
- Get prequalified or preapproved before visiting a dealership.
- Prepare your income, identity, and vehicle documents.
- Review the final terms, insurance requirements, and protection options.
A local, personalized approach can make car shopping feel less bureaucratic and give you more control over the deal. At Autobon Motors, we also keep selling simple: 01. Book your Appointment Online, 02. Bring your Car, 03. Get an instant Offer by one of our advisors, and 04. Get Paid on the Spot – which may help clarify your trade-in equity before you finance.
I am Marcos Bravo, a South Florida luxury and exotic automotive sales and marketing professional with more than 25 years of experience helping buyers and sellers navigate vehicle decisions. My work across Fort Lauderdale and Miami has shown me that understanding auto car loans near me before signing helps local drivers avoid pressure and make more confident choices.
Step 1: Check Credit and Calculate Payment Terms for Auto Car Loans Near Me
Before you start browsing dealer inventory across Fort Lauderdale or Miami, your very first move should be looking under your financial hood. Searching for auto car loans near me starts with knowing your credit score and understanding how loan terms affect your total spending power.
Your credit score is the single biggest factor determining the interest rate (APR) lenders will offer you. According to guidance from the Consumer Financial Protection Bureau, credit scores in the auto lending industry fall into distinct tiers:
- Super-Prime & Prime (720–850): Qualifies for the lowest advertised interest rates, often starting below 4.00% to 5.00% APR on new vehicles and under 5.50% APR on recent model used cars.
- Non-Prime (620–719): Receives moderate interest rates. Lenders may ask for a modest down payment or check your debt-to-income (DTI) ratio more closely.
- Subprime & Deep Subprime (300–619): Subprime borrowers can still secure auto financing, but interest rates will be higher. Providing a strong down payment (such as 10% or more) or adding a co-signer helps lower risk for the lender.
Beyond credit scores, lenders weigh your Debt-to-Income (DTI) ratio. Your DTI compares your total monthly debt payments (rent/mortgage, credit cards, student loans) against your gross monthly income. Most local lenders prefer a total DTI below 45% (including your prospective new car loan payment).
When calculating your payment terms, loan length directly impacts your wallet. While extended loan terms—such as 72, 84, or even 96 months—spread your principal over a longer period to make monthly payments appear smaller, they frequently come with higher interest rates and significantly increase total interest paid over time. Furthermore, many lenders enforce minimum loan amounts for extended terms (for example, requiring at least $12,000 for a 72-month term or $25,000 for a 96-month term).
Comparing New vs. Used Vehicle Financing
Financing a brand-new vehicle versus a pre-owned vehicle carries key structural differences:
- Model Year & Mileage Caps: Lenders categorize vehicles by age. New car rates generally apply to current or upcoming model years with under 7,500 miles. Used car rates are split by age tiers (e.g., 2023 and newer vs. 2016–2022 models).
- Depreciation Curve: New vehicles lose value faster during the first 24 to 36 months. While new car loans often carry slightly lower APRs, used car purchases typically require smaller total loan principal, leading to lower overall interest charges over the life of the loan.
Using an online auto loan calculator allows you to test different loan terms (36, 48, 60, or 72 months) alongside various down payment amounts to establish a firm monthly threshold that fits comfortably into your budget.
Step 2: Compare Local Lenders: Credit Unions, Banks, and Dealerships
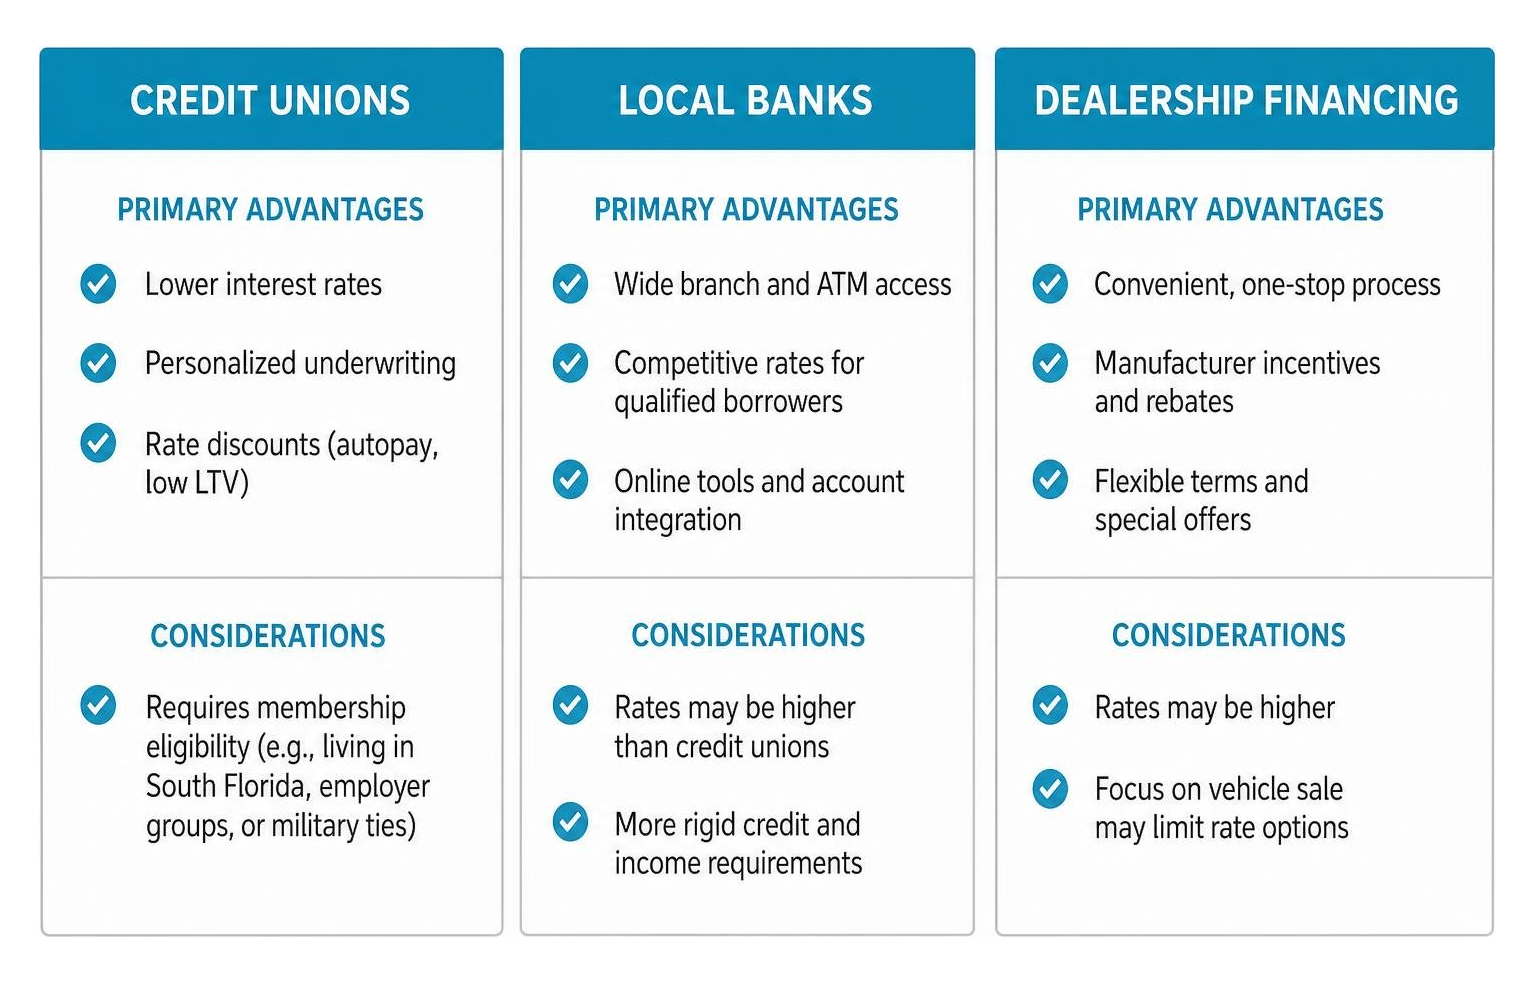
When seeking auto car loans near me in Broward County or anywhere in South Florida, you have three primary lending channels to evaluate. Each option comes with distinct advantages depending on your credit profile and buying style.
| Lender Type | Primary Advantages | Considerations |
|---|---|---|
| Local Credit Unions | Lower interest rates, personalized underwriting, rate discounts (autopay, low LTV), community focus | Requires membership eligibility (e.g., living in South Florida, employer groups, or military ties) |
| Commercial Banks | Convenience for existing checking/savings account holders, robust mobile banking apps | Stricter automated credit scoring models; slightly higher baseline APRs for used cars |
| Dealership Financing (Indirect) | One-stop shopping, direct access to manufacturer promotional APRs, flexible subprime programs | Lenders pay dealers participation fees; requires vigilance during finance desk negotiation |
Credit Unions vs. Local Commercial Banks
Credit unions are member-owned, non-profit financial institutions. Because profits are returned to members, credit unions consistently offer some of the most competitive auto loan rates in South Florida. For example, local credit union rates for excellent-credit borrowers routinely start between 3.89% and 4.99% APR for new cars, with terms up to 60 months. Furthermore, credit unions frequently offer helpful incentives, such as:
- 0.50% Autopay Discounts: Lowering your APR simply by setting up automatic monthly loan transfers from a linked checking account.
- Low Loan-to-Value (LTV) Discounts: Rate reductions of 0.50% to 1.00% when your loan amount is significantly less than the vehicle’s retail value (LTV under 115%).
- First-Pay Delays: Programs that allow qualified borrowers to defer their first payment for up to 60 days post-purchase.
Commercial banks offer quick digital approvals and seamless integration if you already manage checking or savings accounts with them. However, banks often rely on automated underwriting algorithms that may penalize minor credit blemishes, whereas local community financial institutions may offer human-based underwriting decisions within 24 hours.
Indirect Dealership Financing & Special Offers
When you finance through a dealership’s finance department, the dealer acts as an intermediary, submitting your application to a network of regional and national lenders. Dealership financing is convenient and offers unique access to special manufacturer promotional rates on select inventory.
However, dealerships may add a markup to the wholesale interest rate approved by the lender as compensation for arranging the financing. To protect your wallet, always secure an independent preapproval from a local bank or credit union before stepping into a showroom. Having an approved rate in your pocket gives you strong leverage to negotiate or ask the dealer’s finance department to beat your existing offer.
Military service members, veterans, and their families living in South Florida should also ask lenders about dedicated military discounts, which can include special APR reductions, low-down-payment options, or cash bonuses when transferring an auto loan from another lender.
Step 3: Get Prequalified and Pre-Approved Online
Once you have identified potential local lenders, the next step is securing conditional financing before visiting vehicle lots. Securing preapproval streamlines the process, transforming you from a hopeful shopper into a empowered cash-equivalent buyer.
To find the right vehicle before securing your rate, you can explore top local dealership financing solutions in the Fort Lauderdale area.
Prequalification vs Preapproval for Auto Car Loans Near Me
Many buyers confuse prequalification with preapproval, but they serve very different purposes during your car-buying journey:
Prequalification (Soft Credit Inquiry):
- How it works: You submit basic income and debt estimates online.
- Credit Impact: Lenders perform a soft credit check, which does not impact your FICO credit score.
- Outcome: Gives you a rough, non-binding estimate of what you might be able to borrow and an approximate interest rate range. Great for early budget planning.
Preapproval (Hard Credit Inquiry):
- How it works: You submit verified personal identification, employment details, housing expenses, and social security details.
- Credit Impact: The lender conducts a hard credit check, which may temporarily lower your credit score by a few points.
- Outcome: A formal, conditional loan commitment specifying your maximum loan amount, approved interest rate, and term length.
Pro-Tip: Credit scoring bureaus recognize that consumers shop around for auto loans. Multiple hard credit inquiries for an auto loan conducted within a 14-to-45-day window are typically treated as a single credit event, minimizing the impact on your score.
How to Apply Online or Via Mobile App
Applying for an auto loan online or through a lender’s mobile banking app takes only a few minutes. Most local digital applications follow a straightforward sequence:
- Instant Credit Decision: Automated systems or local underwriters often provide an approval decision within seconds to 24 hours.
- Preapproval Check Validity: Preapproval commitments typically remain valid for 90 calendar days. This gives you a three-month window to shop for the right car in South Florida without re-applying.
- Flexible Vehicle Selection: When applying online before choosing a specific car, simply select “No” or “Undecided” when prompted for exact vehicle make and model details.
- Blank Draft / Direct Check Delivery: Upon preapproval, credit unions and banks issue a preapproved draft check or digital approval voucher up to your maximum loan cap. You take this draft directly to the dealer to complete your purchase.
Step 4: Gather Required Documents and Evaluate Loan Rates

To finalize your auto loan application without unexpected delays, assemble your financial documentation ahead of time. Having these records organized allows local underwriters to process your file smoothly.
Checklist of Required Loan Documents
- Valid Driver’s License: Proof of identity and age (must show current residence address).
- Proof of Income: Recent pay stubs (covering the last 30 days), W-2 forms, or two years of complete tax returns if self-employed.
- Proof of Residence: A recent utility bill (electricity, water) or lease agreement matching your application address in Florida.
- Vehicle Identification Details (VIN): Exact 17-character VIN, exact odometer mileage, year, make, model, and dealer purchase agreement or bill of sale.
- Current Insurance Verification: Proof of active auto insurance policy listing proper coverage limits.
Evaluating Rates and Loan-to-Value (LTV) Ratios
When reviewing formal loan offers, look closely at the Loan-to-Value (LTV) ratio. LTV expresses the loan amount as a percentage of the vehicle’s official appraised market value (calculated using the lowest of MSRP, Kelley Blue Book retail value, or actual purchase price).
$$text{LTV Ratio} = left( frac{text{Total Loan Amount}}{text{Vehicle Market Value / MSRP}} right) times 100$$
For example, if a pre-owned vehicle has an established retail market value of $20,000, and you request a loan of $18,000 (after down payment and trade-in), your LTV is 90%.
Lenders reward lower LTV ratios with lower interest rates because the vehicle provides sufficient collateral equity. Conversely, financing taxes, dealer fees, extended warranties, and negative trade-in equity pushes your LTV above 100% or 115%, increasing lender risk and raising your APR.
Step 5: Finalize Financing and Secure Vehicle Protection
Once you select your vehicle and agree on a purchase price, your lender will establish final funding requirements. This stage includes establishing mandatory insurance coverage, setting up payment schedules, and evaluating optional protection options.
Lenders requiring full coverage auto insurance on financed vehicles almost universally enforce two main constraints:
- Deductible Caps: Comprehensive and collision deductibles must usually be set at $1,000 or lower.
- Loss Payee Designation: The lender must be officially listed as the primary Loss Payee / Lienholder on your insurance binder prior to funding disbursement.
Failing to maintain continuous full coverage auto insurance allows lenders to force-place Collateral Protection Insurance (CPI). CPI is expensive and protects only the lender’s financial interest in the physical vehicle structure—it does not provide liability protection or cover bodily injury.
To review more strategies on navigating finance offices safely, explore our detailed Car Financing Survival Guide.
How to Refinance Existing Auto Car Loans Near Me
If you already have a vehicle loan with a high interest rate, refinancing through a local financial institution in South Florida can lower your monthly commitment or shorten your remaining loan term.
- When to Refinance: Consider refinancing if market interest rates have dropped, your credit score has improved by 30+ points since initial purchase, or you accepted sub-optimal dealer financing on impulse.
- Requirements for Refinancing: You will need a 10-day payoff quote from your existing lender (including account number and daily interest charges), vehicle registration, current mileage, and proof of income. Lenders typically refinance loans up to 90% or 100% of the vehicle’s current NADA retail value.
- Refinance Incentives: Many local credit unions offer cash incentives—such as a $200 refinancing bonus—when transferring a car loan of $5,000 or more from an outside lender.
Understanding GAP Insurance and Protection Plans
When financing a vehicle with a low down payment or extended repayment terms, the vehicle’s market value depreciates faster than your loan balance drops during the first few years. This leaves you “upside-down” or in negative equity.
- Guaranteed Asset Protection (GAP Insurance): If your vehicle is totaled in an accident or stolen, standard auto insurance pays out only the current fair market value of the car. If your remaining loan balance is higher than the insurance payout, you are responsible for paying the difference out of pocket. GAP insurance covers this financial gap.
- GAP Advantage Perks: Certain local financial protection plans offer enhanced GAP coverage that pays off the remaining loan balance and provides a $1,000 credit toward financing your replacement vehicle with the same lender.
- Mechanical Breakdown Protection (MBP): An optional service contract that covers unexpected mechanical and electrical repairs after manufacturer factory warranties expire, often available at lower costs through credit unions than traditional dealership service contracts.
Frequently Asked Questions
How long does it take to get approved for a local auto loan?
Most local banks and credit unions deliver automated online preapproval decisions within minutes. If an application requires manual human underwriting—such as verifying complex self-employment income or reviewing unique credit situations—the process usually takes up to 24 hours. Once approved, funds or draft checks can be picked up in person at a local branch or delivered electronically within one business day.
Can I get an auto loan with bad credit or no credit history?
Yes. Specialized subprime auto loans exist for borrowers with credit scores in the non-prime or subprime ranges (300 to 580) or those building credit for the first time. To maximize your approval chances and secure a lower interest rate:
- Provide a substantial cash down payment (10% to 20%) to lower the Loan-to-Value ratio.
- Apply with a creditworthy co-signer (such as a family member with strong credit).
- Choose a reliable pre-owned vehicle with lower mileage to keep total loan risk manageable.
Are there special auto loan discounts for military members or veterans?
Yes. Many credit unions and regional banks across South Florida offer dedicated military incentives. Active duty service members, reservists, veterans, and military family members can access discounted APR tiers, flexible terms, zero-application-fee structures, and refinancing cash bonuses ($200+). Always inform your lender of your military affiliation before finalizing terms.
Conclusion
Securing the best auto car loans near me comes down to preparation, clear information, and choosing local partners who prioritize straightforward communication over bureaucratic delays. By checking your credit early, comparing credit unions against traditional banks, securing online preapproval, organizing required documents, and understanding insurance protections, you keep full control over your car purchase.
At Autobon Motors, located right in Fort Lauderdale, we believe every step of buying or selling a car should be simple, transparent, and tailored to South Florida drivers. If you have an existing vehicle to sell or trade in before securing your next auto loan, our personalized process avoids the impersonal corporate runaround:
- 01. Book your Appointment Online: Pick a time that fits your schedule.
- 02. Bring your Car: Visit our comfortable Fort Lauderdale location.
- 03. Get an instant Offer by one of our advisors: Receive a fast, fair, human appraisal in just 15 minutes.
- 04. Get Paid on the Spot: Walk away with cash or apply your trade equity directly toward your next vehicle purchase.
Ready to take control of your vehicle financing journey? Learn how to Apply for Auto Loan in 5 Easy Steps or visit Autobon Motors today to unlock the full equity in your current ride!